

FINANCE FOR
RESIDENTIAL.
Give your customers access to flexible finance for solar & storage.
More payment options in your proposals.
Segen Finance allows homeowners to spread the cost of a solar and storage installation directly within the proposal tool, powered by Zopa Bank – with no FCA license required.
How retail finance works
Increased Sales Conversion
Enabling additional payment options for homeowners increases installers’ ability to convert on a sale, allowing installers to complete more projects and grow their business.
No FCA licence is required
Finance is presented in the proposal and discussions are between Segen Finance, the credit broker, Zopa Bank, the lender and the homeowner, allowing installers to focus on the installation.
No upfront payment
When homeowners are approved for finance, hardware is delivered without requiring upfront payment or using credit, allowing installers to protect their cash flow and credit lines.
How a finance order works, step by step.
A short walkthrough of how a financed order works.
See how homeowners select finance inside the proposal, why delivery waits until the 14-day cool-off has passed, and how signing the completion certification releases payment.

Homeowner benefits
A summary of the key benefits that retail finance can give to homeowner customers.
- Flexible Payment Terms – Homeowners can choose to pay monthly for their solar installation over time, rather than in one single payment, making solar more affordable.
- Finance is offered directly in the Segen proposal tool – Homeowners apply for financing directly in the proposal they have already been sent, creating a simple and streamlined credit application process.
- Quick decision – Homeowners only need to answer 9 questions to apply, getting a decision instantly on if they have been approved, with no impact to their credit score.
How to get set up
Onboarding Requirements – There are five key requirements that must be met to enable finance in your Segen proposal.
MCS Certification
To offer financing you must have MCS certification.
Comprehensive Insurance
Adequate insurance coverage protects both you and the end customer.
Trading History With Segen
We check your order and payment history to ensure you have an established, reliable trading relationship with us.
A Zopa Account To Receive Payment
You will need an account with our banking partner for you to receive funds. Segen Finance will guide you through the set up process.
Installer Identity Checks
Zopa will run KYC checks on anyone with a 25%+ ownership of your company, including Director verification and proof of business address.
Available through Renewables Studio.
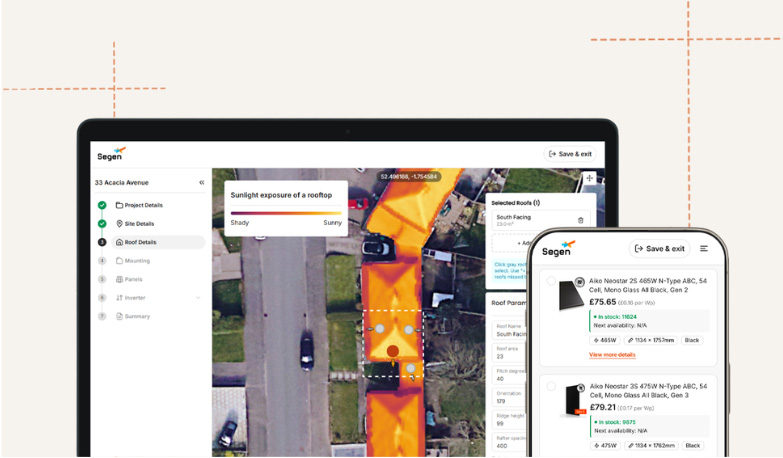
Segen Finance is available through the Proposals Tool, part of Renewables Studio. Once an installer has successfully completed Segen Finance onboarding, the finance option appears within the customer proposal.
- DESIGN
- PROPOSAL
- FINANCE
Your role and where it ends.
Installers must not discuss, explain, promote or advise on the finance product with homeowners. Finance questions should be directed to Segen Finance / the lender as appropriate. The installer’s role is to generate and send the proposal; the finance conversation and credit application are handled separately.
Residential Finance FAQs
Here are our answers to the questions installers commonly ask us. Anything about rates or monthly payments is answered for the homeowner inside the proposal tool or directly with Zopa Bank.
Contact: Segenfinance@segen.co.uk
Q: What can I say if a homeowner asks about interest rates, APR, or the total repayment amount?
A: You can confirm that a finance option is included in their proposal and that the full details are set out there. However, as you are not licenced by the FCA, you are not allowed to talk about anything relating to finance. Direct any further questions to Zopa Bank, they are the lender and will hold all of the relevant details relating to the financing option.
Q: Can I market the financing product or recommend the finance option to a homeowner?
A: No, as you are not a licenced credit broker or lender, you are not allowed to market or discuss anything relating to finance, including suitability, affordability or comparisons with other financing products. Any conversations about finance are between the homeowner and Zopa Bank only.
Q: If a homeowner chooses to pay via finance in their proposal ,what do I need to do?
A: You do not need to do anything. The homeowner is automatically directed to the banks credit application portal to fill out their details. If approved, you will be notified to contact the customer about the installation date and you can proceed to convert the hardware quote into an order.
Q: A homeowner has asked me to compare the Segen Finance quote with another, what do I do?
A: As you are not licenced as a credit broker, you are not allowed to discuss or compare finance quotes. Direct the homeowner to the details in their proposal, or to contact Zopa Bank directly.
Q: Who do I contact if there is an issue with the proposal tool?
A: Contact your Sales Manager, including a description of the issue and if appropriate the proposal reference, who will be able to direct it to the appropriate internal channel.
Q: What to do if a homeowner has told me the finance figures in the proposal look wrong?
A: Contact your Sales Manager with details on exactly what the homeowner has told you and the proposal reference. In the meantime, let your homeowner customer know that the issue is being investigated.
Q: How do I know if my homeowner customer has been approved for finance?
A: Once the homeowner has been approved by Zopa Bank, they will be redirected back to their proposal and directed to contact you, to organise an installation date. You will also be notified to contact them and to convert your hardware quote into an order, taking into account the 14-day cool off period. Notification happens both via email and within the project section of your proposal tool dashboard.
Q: What is the cooling-off period, and can I book a delivery or installation date before it ends?
A: The cool-off period is a statutory right every consumer has to cancel a financing agreement once approved and it lasts for 14 days. Once Zopa approves a finance application, the cool-off period automatically begins. No delivery of hardware or installation can occur within this window, however, the hardware quote can be converted to an order and delivery can still be scheduled for when the cool-off period finishes.
Q: What happens if the homeowner cancels during the cooling-off period?
A: The order will be cancelled, and no invoice is raised or stock allocated. You will be notified when this happens. Projects can still proceed via the cash route in this instance.
Q: I have completed the job and it has been signed off by the homeowner; however, I can’t see the funds in my bank account yet, what’s happening?
A: Once the homeowner signs off the installation, the bank releases funds into a Segen holding account. This is split into two to cover the hardware costs, and all other elements of the project. Funds due to you will be sent to your Zopa account and are cleared to your own bank account once a day, in the evening. It may take up to two days to appear in your account, depending on when the transfer occurs. If it has not appeared in your account after this time, please contact your Sales Manager.
Q: Where do I find my VAT invoice for a financed order?
A: VAT invoices will be sent to you once the hardware has shipped as per usual. You will also be able to download the invoice within your installer account.
Q: What if there’s a defect or an issue the homeowner wants fixed before they sign off?
A: The homeowner is able to raise any issues directly with you before signing the Certificate of Acceptance. All issues need to be resolved first before sign off can happen and payment released.
Q: What if a homeowner raises a complaint?
A: If the homeowner has a complaint, please identify its nature (e.g. poor installation, broken hardware, damage to roof, finance was misrepresented, loan agreement is misleading etc). Once you have identified the nature of the complaint, please contact Segen Finance and Zopa Bank directly. All complaints need to be investigated through a specific process and it is not your role to decide something is not a complaint. An FCA regulated complaint differs from a installation complaint and will be dealt with by the credit broker or lender in the appropriate manner.
Ready to get set up for Segen Finance?
To access Segen Finance, you’ll need to have a Segen account and complete domestic installations. Complete the form below and our team will be in touch to guide you through the next steps.
For Complaints:
Financial Ombudsman Service
Address: The Financial Ombudsman Service, Exchange Tower, London E14 9SR
Email: complaint.info@financial-ombudsman.org.uk
Website: www.financial-ombudsman.org.uk
Tel: 0800 023 4567 (free for most people ringing from a fixed line) or 0300 123 9123 (cheaper for those calling using a mobile) or 44 20 7964 0500 (if calling from abroad)
Segen Finance is a trading name of Segen Ltd, authorised and regulated by the Financial Conduct Authority (Firm Reference Number 1013386). Credit is provided by Zopa Bank Limited, the lender, and subject to status and affordability checks. Segen Finance is a credit broker, not a lender. We may receive remuneration by way of commission for our credit broking activities, details of which can be provided upon request. Zopa Bank Limited is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority.